
The fitment factor is one of the most closely watched numbers ahead of the 8th Pay Commission because it will play an important role in determining revised basic pay.
However, there is a common misunderstanding about what a higher fitment factor actually means.
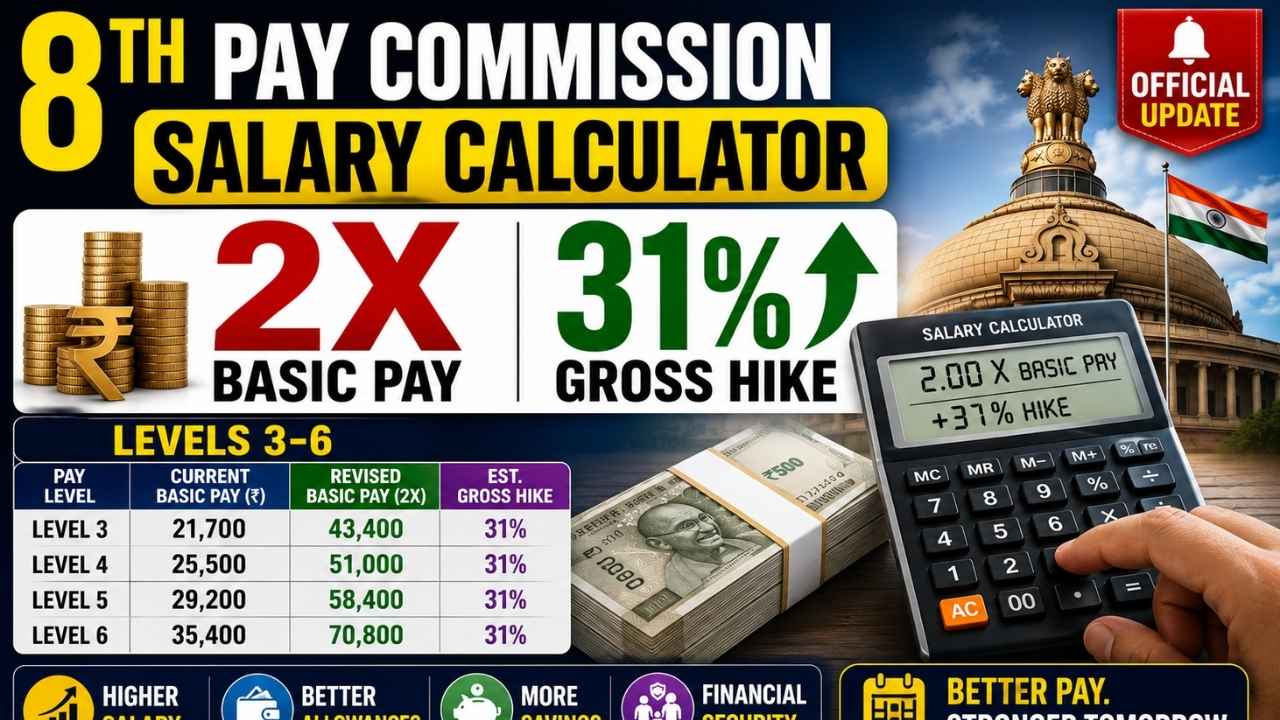
A fitment factor of 2.0 would double an employee’s basic pay under a simple calculation. But that does not mean the employee’s gross salary will also double.
Gross salary includes several components beyond basic pay, including dearness allowance, house rent allowance and transport related allowances. The treatment of these components under the revised pay structure can significantly change the final salary increase.
What Is the Fitment Factor?
The fitment factor is essentially a multiplier used to arrive at revised basic pay under a new Pay Commission.
For example, if an employee currently has a basic pay of ₹30,000 and a fitment factor of 2.0 is applied, the resulting revised basic pay would be ₹60,000.
The calculation looks simple:
Current basic pay × Fitment factor = Revised basic pay
But an employee’s monthly salary is not made up of basic pay alone.
That is why the fitment factor should not be treated as the percentage increase in take home or gross salary.
Why a 2.0 Fitment Factor Does Not Mean Salary Will Double
Suppose an employee currently receives ₹30,000 as basic pay along with DA, HRA and other allowances.
If the fitment factor becomes 2.0, the basic component could rise to ₹60,000.
That is a 100% increase in basic pay.
However, the employee’s existing DA may be absorbed or reset under the new pay structure. HRA and other allowances may also be recalculated using the revised basic pay and new rates.
As a result, the total salary increase can be substantially lower than 100%.
This distinction is important when estimating what an employee may actually receive after the 8th Pay Commission recommendations are implemented.
What Happened Under the 6th and 7th Pay Commissions?
Past Pay Commissions demonstrate why the fitment factor cannot be used by itself to predict gross salary growth.
The 6th Pay Commission used a fitment factor of 1.86. However, the average gross pay increase was considerably lower than what someone might expect from simply applying that multiplier.
The 7th Pay Commission used a higher fitment factor of 2.57.
Yet the increase in average gross salary was nowhere near 157%.
The reason is that the fitment factor primarily affects basic pay. DA and other allowances have their own calculations and can change when a new pay structure is introduced.
What Happens to DA Under a New Pay Commission?
Dearness allowance is another crucial part of the calculation.
For an illustration involving the 8th Pay Commission, if the existing DA is assumed to be 60%, simply carrying that 60% forward after applying the fitment factor would produce a misleading result.
A new Pay Commission can introduce a revised pay structure in which DA is reset and then begins accumulating again under the new system.
Therefore, employees should not calculate their future salary by taking their current gross salary and multiplying it by 2.0.
That approach would significantly overstate the potential increase.
Level 3 Employee: What Could a 2.0 Factor Mean?
Consider a Level 3 employee whose current basic pay is ₹21,700.
Using the assumptions in the supplied illustration, the current estimated gross salary is around ₹41,230.
With a 2.0 fitment factor, the revised basic pay would become:
₹21,700 × 2.0 = ₹43,400
Under the stated assumptions for allowances, the estimated gross salary would be approximately ₹53,816.
That means basic pay would double, but gross salary would rise by around 31%.
This example clearly shows why a 2.0 fitment factor should not be interpreted as a 100% increase in total salary.
Level 4 Employee: What If the Fitment Factor Is 2.38?
A Level 4 employee with a current basic pay of ₹25,500 provides another useful illustration.
At a fitment factor of 2.38, the revised basic pay would be approximately ₹60,690.
The estimated current gross salary under the assumptions is ₹48,450.
After applying the assumed revised salary structure, the estimated gross salary could reach around ₹75,256.
The basic pay would therefore increase by about 138%, while gross salary would increase by approximately 55%.
Again, the two percentages are very different.
Level 5 Employee: A Higher Factor Changes the Calculation
For a Level 5 employee, the supplied illustration starts with a basic pay of ₹29,200 and an estimated gross salary of ₹55,480.
At a 2.57 fitment factor, the revised basic pay would become approximately ₹75,044.
Under the stated assumptions, estimated gross salary would reach about ₹93,055.
The basic pay increase works out to roughly 157%, whereas the gross salary increase is approximately 68%.
This is another example of why basic pay and gross pay need to be examined separately.
Level 6 Employee: 2.57 Fitment Factor Example
The same principle can be seen at Level 6.
The current basic pay in the illustration is ₹35,400, with estimated gross salary of ₹67,260.
Applying a 2.57 fitment factor gives a revised basic pay of approximately ₹90,978.
The estimated gross salary under the assumptions rises to around ₹1,12,813.
This represents an increase of about 157% in basic pay but approximately 67.7% in gross salary.
Comparing the Different Fitment Factor Scenarios
The supplied examples can be summarised as follows:
| Pay Level | Current Basic Pay | Fitment Factor | Revised Basic Pay | Estimated Gross Pay |
|---|---|---|---|---|
| Level 3 | ₹21,700 | 2.00 | ₹43,400 | ₹53,816 |
| Level 4 | ₹25,500 | 2.38 | ₹60,690 | ₹75,256 |
| Level 5 | ₹29,200 | 2.57 | ₹75,044 | ₹93,055 |
| Level 6 | ₹35,400 | 2.57 | ₹90,978 | ₹1,12,813 |
These figures are illustrative and depend heavily on the assumptions used for DA, HRA and other allowances.
They should therefore not be treated as final 8th Pay Commission salary figures.
What About HRA?
House Rent Allowance can also make a significant difference to the final calculation.
HRA is generally linked to basic pay and the applicable city category.
If the basic pay changes under the new Pay Commission, the HRA calculation can change as well.
However, the percentage or structure used for HRA under a future revised pay system may not necessarily be identical to the existing arrangement.
That is why any 8th Pay Commission salary calculator available before the final rules are announced should be viewed as an estimate rather than an official salary statement.
Transport Allowance Also Matters
Transport allowance is another component that contributes to gross salary.
The final salary calculation therefore requires more than simply multiplying basic pay by the proposed fitment factor.
The revised basic pay, DA structure, HRA, transport allowance and other applicable components all need to be considered together.
This is also why two employees with the same basic pay can potentially have different gross salaries depending on their applicable allowances and location.
A Higher Fitment Factor Is Not the Only Thing That Matters
Employees naturally focus on the fitment factor because it is an easy number to compare.
For example, 2.0, 2.38 and 2.57 appear dramatically different.
But the final benefit to an employee depends on the entire revised pay structure.
A lower fitment factor accompanied by more favourable allowance calculations could produce a different outcome from what a simple comparison suggests.
Similarly, a high fitment factor does not automatically guarantee that the final gross salary will increase by the same percentage.
What Employees Should Wait For
The final salary calculation will depend on the official recommendations and the government’s eventual decisions on the revised pay structure.
Until the applicable pay matrix, fitment factor and allowance rules are officially settled, salary calculations remain estimates.
Employees should therefore be cautious about social media posts claiming that a particular fitment factor will definitely produce a specific monthly salary.
The calculation can change considerably depending on assumptions about DA, HRA and other allowances.
Final Takeaway
A 2.0 fitment factor would be significant because it would double basic pay under a straightforward multiplier calculation.
But doubling basic pay does not mean doubling gross salary.
The experience of previous Pay Commissions shows that the relationship between the fitment factor and the final salary is more complicated. DA can be reset, HRA can change and other allowances can be recalculated under the new pay structure.
Based on the illustrative figures provided, a 2.0 fitment factor could result in a much smaller increase in gross salary than the 100% increase in basic pay might suggest.
For employees waiting for the 8th Pay Commission, the most important figure will therefore not be the fitment factor alone. The complete revised pay structure and the treatment of DA, HRA, transport allowance and other components will determine how much the salary actually changes.
The calculations above are illustrative and based on the assumptions stated in the supplied figures. They should not be considered an official 8th Pay Commission salary calculation.