
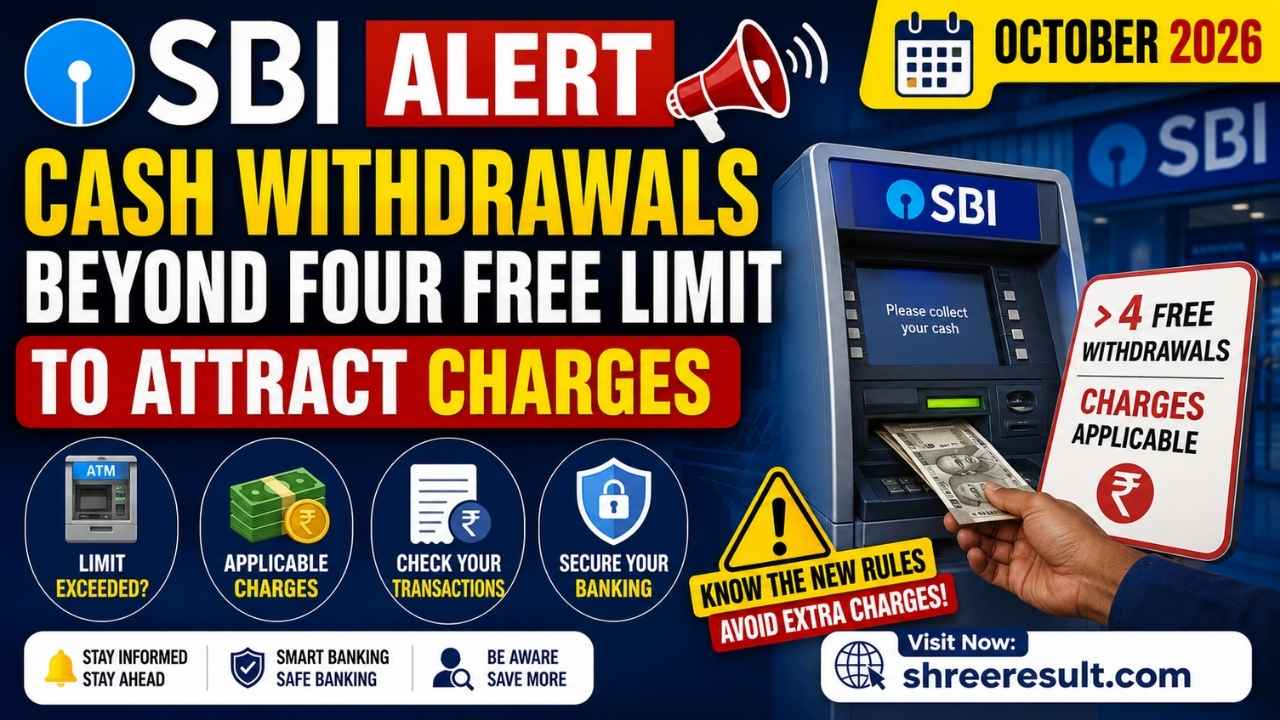
SBI customers who use a Basic Savings Bank Deposit account will have a new cash withdrawal rule to keep in mind from October 1, 2026.
The change is relatively simple, but it could matter to customers who frequently take out cash during the month. State Bank of India has revised the service charges applicable to certain BSBD account transactions, with the new structure taking effect from October 1.
The biggest point to remember is that the first four eligible cash withdrawals in a month will remain free. Once those four transactions have been used, an additional cash withdrawal will attract a charge of ₹15, along with applicable GST.
For customers who rarely withdraw cash, the change may have little practical effect. Those who regularly use cash, however, may need to keep a closer watch on their monthly transactions.
What Is Changing for SBI BSBD Account Holders?
The revised structure does not mean that SBI is going to charge customers for every cash withdrawal.
Instead, the bank is keeping a limited number of free transactions and introducing a fee once that limit has been crossed.
A BSBD account holder can make four eligible cash withdrawals during a month without attracting this additional charge.
The fifth eligible withdrawal is where the revised fee becomes relevant.
Every eligible withdrawal after the four free transactions can attract ₹15 plus applicable GST.
This makes the number of withdrawals more important than the amount withdrawn.
For instance, withdrawing ₹500 five separate times can result in a charge after the fourth transaction, while a customer who makes fewer withdrawals may remain completely within the free limit.
The Charge Is Per Additional Withdrawal
One detail customers should understand clearly is that ₹15 is not a one-time monthly fee.
The charge applies to each eligible cash withdrawal made after the free transactions have been exhausted.
Suppose a customer makes seven eligible cash withdrawals in one month.
The first four remain within the free limit. The fifth, sixth and seventh withdrawals fall outside that limit and can each attract the ₹15 charge plus applicable GST.
As a result, customers who frequently withdraw small amounts could accumulate several charges during the same month.
Which SBI Accounts Does This Change Concern?
The revised rule is specifically related to Basic Savings Bank Deposit accounts.
It should not be interpreted as a new cash withdrawal fee that automatically applies to every SBI savings account.
This distinction is important because SBI offers several types of deposit accounts, each with its own service-charge structure.
Customers who are unsure about their account category should check their account details and the latest SBI service-charge schedule before assuming that the BSBD rules apply to them.
Why Frequent Cash Users Need to Be Careful
For someone who withdraws cash once or twice a month, four free transactions may be more than enough.
The situation is different for customers who depend heavily on cash.
A person may withdraw money several times because of household expenses, local purchases or other regular needs. Even relatively small withdrawals count as separate transactions when they fall within the applicable withdrawal category.
This means customers should not focus only on how much money they withdraw.
The number of withdrawals matters too.
Someone withdrawing ₹10,000 in one transaction and someone withdrawing ₹2,000 five times are using the cash withdrawal facility very differently from a transaction-count perspective.
AePS Cash Withdrawals Also Matter
Customers using the Aadhaar Enabled Payment System, or AePS, should pay particular attention to the revised arrangement.
AePS cash withdrawals will also be counted when determining the monthly free cash withdrawal limit.
This means customers should not assume that an AePS withdrawal is completely separate from withdrawals made through other eligible channels.
A customer could use an ATM on one occasion, withdraw cash through a branch on another occasion and use AePS later in the month. These transactions can all become relevant when calculating the free withdrawal allowance.
For people who regularly use AePS to access cash, this is an important change to understand.
Digital Payments Are Different
The revised cash withdrawal charge should not be confused with a charge on digital transactions.
Customers who use digital payment methods for their everyday spending are not using up the four cash withdrawal transactions simply by making digital payments.
This could make the change less noticeable for people who already rely on UPI, online transfers and other electronic payment methods.
The new charge is linked to eligible cash withdrawals, not ordinary digital payments.
For customers who have access to digital payment options, using them where practical can also reduce the need for frequent cash withdrawals.
A Simple Example
Consider an SBI BSBD account holder who makes four cash withdrawals during October.
The customer has used all four free transactions.
A few days later, the customer needs cash again and makes another eligible withdrawal.
That fifth transaction is outside the free monthly limit and can attract ₹15 plus applicable GST.
If the customer withdraws cash again later in the same month, that transaction can also attract the charge.
The important point is that the free limit does not reset after the fifth transaction. The customer has already used the four free withdrawals for that month.
The Amount Withdrawn Does Not Determine the Free Limit
Another point worth remembering is that the number of transactions is central to this particular charge.
Customers should not assume that a small withdrawal will be ignored simply because the amount is low.
If it is an eligible cash withdrawal and the monthly free limit has already been exhausted, the applicable charge can arise regardless of whether the amount withdrawn is relatively small.
This is why keeping track of transaction frequency can be more useful than simply keeping track of the total amount withdrawn.
Planning Withdrawals Could Help Customers
Customers who frequently use cash may want to plan their withdrawals more carefully once the revised rules take effect.
Instead of making several small withdrawals throughout the month, some people may find it more convenient to combine their cash requirements when possible.
This will not be practical in every situation, and customers should withdraw money according to their actual needs.
The point is simply to avoid unnecessary transactions after the free limit has been used.
A little planning could help customers avoid charges that they were not expecting.
Will This Affect Every BSBD Customer?
No.
The impact will depend on how a customer uses the account.
Someone making one, two or three eligible cash withdrawals in a month would remain below the four-transaction threshold.
A customer making exactly four would also remain within the free limit.
The additional cost becomes relevant only when the applicable number of free transactions has been exceeded.
Therefore, the revised rule is much more significant for frequent cash users than for customers who mainly use their BSBD account for deposits, digital payments and occasional withdrawals.
There Is No Need to Panic About Existing Savings
The announcement should not be interpreted as a reason for customers to immediately close their BSBD accounts.
The change concerns a particular service and a particular transaction limit.
Customers should first consider how often they actually use cash withdrawal facilities.
If their normal usage stays within four eligible withdrawals per month, the revised charge may not affect them at all.
If they regularly exceed the limit, they can decide whether changing their transaction habits or using digital payment options where appropriate would be more convenient.
What Customers Should Check Before October
With the new rule approaching, BSBD account holders should first confirm that they actually have a BSBD account.
They should then understand how many eligible cash withdrawals they normally make each month.
Customers who use more than one withdrawal method should also remember that AePS transactions can count toward the applicable limit.
Finally, it is worth checking SBI’s latest official service-charge information before making assumptions based on older articles or information shared on social media.
Bank charges can be revised, and the latest official schedule should always take priority.
The Bottom Line
SBI’s revised BSBD cash withdrawal structure is mainly a concern for customers who frequently access their money in cash.
From October 1, 2026, the first four eligible cash withdrawals in a month will remain free. After that, each additional eligible cash withdrawal can attract a ₹15 service charge plus applicable GST.
AePS cash withdrawals will also be relevant to the monthly transaction count, while ordinary digital transactions are not subject to this four-withdrawal cash limit.
For customers who rarely withdraw cash, the change is unlikely to make much difference.
For frequent cash users, however, keeping track of monthly withdrawals will become more important. Knowing the limit in advance can help avoid unnecessary charges and make it easier to decide when to withdraw cash and when to use digital payment options instead.