
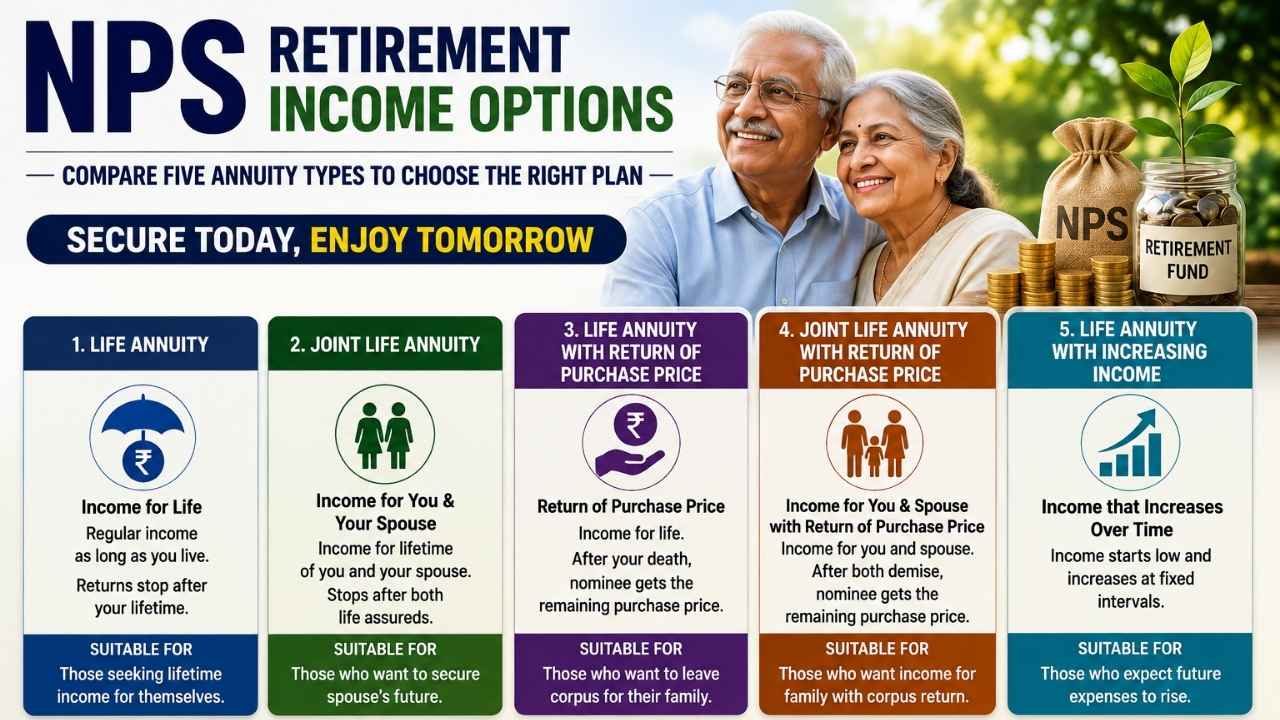
Retirement planning does not end when your NPS account reaches maturity. For many subscribers, an equally important decision begins at that point: deciding how the annuity portion of the accumulated retirement corpus should be used.
An annuity converts part of your retirement savings into a regular income. Depending on the option selected, the income may continue only during your lifetime, pass to your spouse after your death, or provide a benefit to your nominee.
This makes the choice more important than simply comparing the highest monthly payout.
What Happens to Your NPS Corpus at Retirement?
At the normal exit age, an NPS subscriber can take a portion of the accumulated corpus as a lump sum, while the remaining amount is used for purchasing an annuity, subject to the applicable NPS rules.
Under the commonly applicable framework, at least 40% of the accumulated pension wealth is used for annuity purchase at normal exit.
The annuity is purchased from an authorised Annuity Service Provider, and the selected product determines how the retirement income will be paid.
The remaining eligible portion can be received as a lump sum, subject to the prevailing NPS rules and conditions.
This means retirees need to think about two separate requirements: immediate access to retirement savings and dependable income for the years ahead.
Why the Annuity Choice Matters
An annuity is designed to provide regular income after retirement. But different annuity structures distribute the money differently.
One plan may provide a higher monthly income but offer little or no benefit to the family after the annuitant’s death.
Another may provide a smaller monthly payment but continue income for the spouse.
Some products are designed to return the original purchase price to the nominee, while others guarantee payments for a specified period.
The right choice therefore depends on your household’s financial requirements rather than simply selecting the product with the biggest initial payout.
Single Life Annuity: Higher Income but No Continuing Benefit
A single life annuity generally provides income to the annuitant for life.
Its major attraction is the potentially higher regular payout compared with options that provide benefits to another person after the annuitant’s death.
However, there is an important trade-off.
When the annuitant dies, the payments normally stop according to the terms of the selected product. If there is no return of purchase price or other death benefit, the family may not receive the original amount used to purchase the annuity.
This structure can therefore be considered by retirees who have independent financial resources and do not have a spouse or other dependent relying on the annuity income.
It may be less suitable for someone whose spouse depends heavily on their retirement income.
Joint Life Annuity: Continuing Support for Your Spouse
For married retirees, a joint life annuity can provide an important layer of financial protection.
Under this structure, the annuity income can continue to the surviving spouse after the primary annuitant dies, depending on the option selected.
The percentage of the original income that continues to the spouse can vary according to the product.
Because the provider potentially has to make payments over the lives of two people, the initial income can be lower than that offered by a comparable single life annuity.
But the lower starting payout can provide something a single life option may not: continued income for the surviving spouse.
For couples who depend on retirement income to meet regular household expenses, this feature can be particularly important.
Return of Purchase Price: Protecting the Nominee
Some retirees are more concerned about leaving an asset for their family than maximising their own monthly income.
For them, an annuity option that provides a return of the purchase price can be worth considering.
Under such an arrangement, the subscriber receives regular income during their lifetime, while the purchase price is returned to the nominee after death according to the terms of the annuity.
The trade-off is generally a lower regular payout compared with a pure life annuity.
This type of plan can appeal to people who want retirement income while also retaining a mechanism for transferring the original annuity purchase amount to their family.
The exact death benefit and conditions vary between products, so the product document should always be examined before making a decision.
Period Certain Annuity: Income for a Fixed Period
Another structure is a period certain annuity.
Instead of focusing entirely on lifetime payments, the product guarantees payments for a predetermined period.
For example, an annuity may provide payments for a specified number of years. If the annuitant dies before the guaranteed period ends, the remaining payments may be made to the beneficiary according to the product’s conditions.
This can be useful for someone who wants to ensure that a minimum period of income is available to the family.
However, retirees should carefully compare the guaranteed period, payout amount and death benefit before selecting such an option.
Increasing Annuity: Starting Lower and Rising Later
Retirement expenses do not necessarily remain constant.
Food, healthcare, housing and other costs can rise over time, which means a fixed pension may gradually lose purchasing power.
An increasing annuity attempts to address this problem by increasing the income at predetermined intervals.
The starting payment is generally lower than that of a level annuity, but the income can rise over the years according to the product’s prescribed increase.
This option may appeal to retirees who are more concerned about maintaining their income over a long retirement than receiving the maximum possible payment during the first few years.
However, an increasing annuity is not automatically the best hedge against inflation. The rate of increase, starting income and overall terms need to be compared carefully.
Should You Choose the Highest Monthly Pension?
Not necessarily.
A high monthly payout can look attractive when comparing annuity illustrations, but the highest initial income may come with fewer benefits for the spouse or nominee.
For example, a single life option might provide more money every month than a joint life or return-of-purchase-price option.
But if your spouse depends on your pension, the larger initial payment may not provide the best overall financial protection for your household.
The decision should therefore consider both current income requirements and what happens after the annuitant’s death.
How Should Married Couples Approach the Decision?
A married retiree should first determine whether the spouse has an independent source of income.
If both partners have sufficient pensions, investments and savings, a higher individual payout may be attractive.
If one spouse relies heavily on the other’s retirement income, protecting the surviving spouse can become a much bigger priority.
In such circumstances, a joint life structure may offer greater financial security even if its initial monthly payout is lower.
The decision should also account for the age of both spouses and their expected retirement expenses.
What If Leaving Money to Children Is Important?
Some retirees want their retirement corpus to generate income without completely giving up the possibility of transferring wealth to their children or other nominees.
An appropriate return-of-purchase-price product may address this objective, depending on its terms.
The important point is to understand exactly what the nominee receives.
A return of purchase price is different from simply transferring the remaining investment value. The product’s terms determine the death benefit and when it becomes payable.
This is why the annuity brochure, benefit illustration and policy terms should be read carefully instead of relying only on the product’s headline name.
Compare Annuity Providers Before Making a Decision
NPS subscribers may have access to annuity products offered by empanelled providers.
The monthly pension offered for the same amount can vary depending on the provider, subscriber’s age, selected annuity structure and other terms.
Therefore, choosing the first available option may not always be appropriate.
Compare the available quotations and examine:
- Initial monthly income
- Joint life benefits
- Return of purchase price
- Guaranteed payment period
- Income escalation
- Payment frequency
- Nominee benefits
- Other applicable terms and conditions
Even a relatively small difference in regular income can become significant over a retirement period lasting many years.
Monthly, Quarterly or Annual Payments?
Annuity income may be available at different payment frequencies depending on the product.
Monthly payments can be convenient for retirees whose household expenses are spread across the month.
Quarterly payments may suit someone who prefers receiving larger amounts less frequently.
Annual payments can work for people who have other sources of monthly income and prefer to receive a larger yearly amount.
The payment frequency should match your actual spending pattern rather than being selected solely on the basis of the headline amount.
Don’t Ignore Taxation
Retirement income should be considered after accounting for taxation.
The tax treatment of annuity income can affect the amount that ultimately remains available for household expenses.
Therefore, retirees should not compare annuity products solely on their gross monthly payout.
The individual’s overall income, applicable tax regime and other sources of retirement income can influence the effective amount available after tax.
For a large retirement corpus, it may be worthwhile to calculate the expected post-tax cash flow before choosing an annuity.
Can You Change Your Mind Later?
This is one of the most important issues to understand before purchasing an annuity.
Annuity selection is generally a long-term decision, and changing or cancelling the arrangement later may not be straightforward.
Once the purchase is completed, the terms of the chosen annuity generally govern the payments and death benefits.
For this reason, retirees should avoid selecting a product simply because it offers the highest initial pension.
Take time to compare the alternatives, understand the nominee benefit and consider how the household would manage if the primary annuitant dies early.
A Simple Way to Choose the Right Option
There is no single annuity that works for every NPS subscriber.
If maximising your own lifetime income is the main objective and you have no financial dependants, a single life option may be worth examining.
If your spouse depends on your retirement income, a joint life option may provide stronger protection.
If passing the original annuity purchase amount to your nominee is important, a return-of-purchase-price structure may be more suitable.
If you want income protection for a specified period, a period certain option may deserve consideration.
And if rising expenses are your biggest concern, an increasing annuity could be evaluated against a conventional level-income plan.
Final Takeaway
Choosing an NPS annuity is not simply a question of finding the highest monthly pension.
The decision affects your retirement income, your spouse’s financial security and the amount that may eventually reach your nominee.
Before purchasing an annuity, compare the available providers and carefully examine the payout structure, death benefit, purchase-price return, payment frequency and applicable conditions.
Most importantly, consider your household’s actual financial situation.
A retiree living independently may value maximum lifetime income, while someone supporting a spouse may prefer an option that continues payments after their death. Another investor may be willing to accept a lower monthly pension in exchange for a benefit for their family.
The best annuity is therefore the one that balances regular retirement income, longevity protection and family security according to your individual circumstances.
Disclaimer: This article is for general informational purposes and is not investment, pension or tax advice. NPS exit and annuity rules, eligibility requirements and product terms can change. Always check the latest PFRDA rules and the terms offered by the relevant Annuity Service Provider before making a retirement decision.