
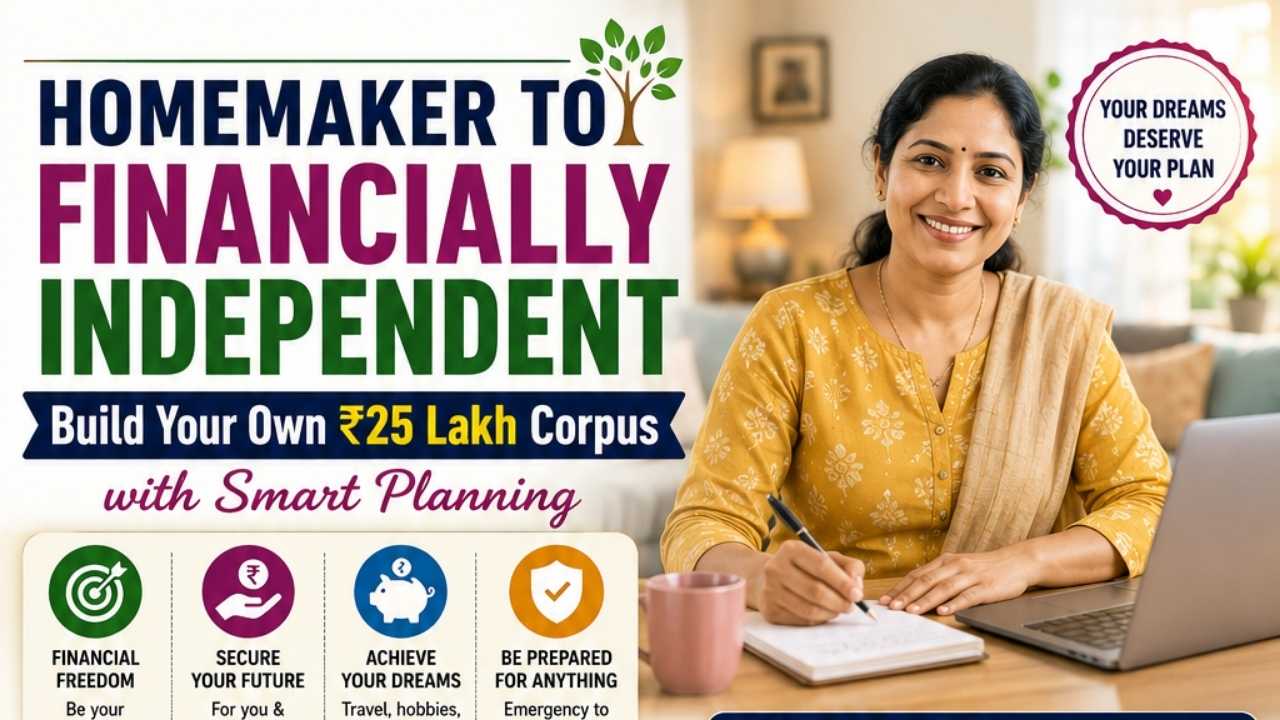
Financial independence is not only for salaried individuals. Homemakers also play an important role in managing household finances, controlling expenses and supporting long-term family goals. Even without a regular monthly salary, disciplined saving and investing can help build a personal financial corpus.
A target of ₹25 lakh may initially appear difficult, but dividing the goal into manageable monthly investments can make it easier to approach. The key is to start according to your financial capacity and remain consistent over the long term.
Why Should Homemakers Build Their Own Financial Corpus?
Having personal savings can provide financial confidence and greater independence. A dedicated corpus can be useful for emergencies, healthcare expenses, personal requirements, retirement planning and unexpected financial situations.
The objective does not have to be reaching ₹25 lakh quickly. Developing a regular saving and investment habit is often more important than starting with a large amount.
How Much Should You Invest Every Month?
The monthly investment required depends on the investment period and the return generated by the investment.
For illustration, assuming a 10% annualised return and monthly investments, the approximate monthly amount required to accumulate ₹25 lakh could be:
| Investment Period | Approx. Monthly Investment |
|---|---|
| 10 years | ₹12,200 |
| 12 years | ₹9,900 |
| 15 years | ₹6,100 |
| 20 years | ₹3,800 |
| 25 years | ₹2,000 |
These figures are only illustrations and do not represent guaranteed returns. Actual market-linked returns can be higher or lower.
The numbers demonstrate one important advantage of starting early. A longer investment period can reduce the amount that needs to be invested every month.
Start With a Comfortable Amount
You do not necessarily need to begin with a large monthly investment.
If your available savings allow you to invest ₹2,000 or ₹3,000 per month, you can start with that amount and gradually increase it as your financial situation improves.
For example, you could increase your monthly investment by 5% or 10% every year whenever household finances permit.
This approach can help increase the final corpus without putting excessive pressure on the monthly household budget.
Where Can Homemakers Invest?
The appropriate investment depends on the goal, investment period, liquidity requirement and risk tolerance.
Bank Fixed Deposits
Fixed deposits can be useful for investors who prefer predictable returns and relatively simple products.
Before opening an FD, compare the applicable interest rate, tenure, premature withdrawal conditions, taxation and deposit insurance provisions.
Public Provident Fund
PPF can be considered for long-term savings. It has a long-term structure and government-backed framework, but its withdrawal and maturity rules mean that it is generally more suitable for long-term goals rather than immediate financial requirements.
Mutual Fund SIPs
Systematic Investment Plans can help investors invest a fixed amount regularly in mutual funds.
For long-term goals, equity-oriented funds may provide higher growth potential, but they also carry market risk. Therefore, SIP investments should be selected according to the investor’s risk capacity and time horizon.
National Pension System
NPS can be considered for retirement-focused investing. It provides a structured retirement investment framework, although specific withdrawal and annuity rules apply.
Therefore, NPS should generally be viewed as a retirement planning instrument rather than an emergency savings option.
Build an Emergency Fund First
Before focusing entirely on the ₹25 lakh target, it is important to establish an emergency fund.
The fund can help cover essential household expenses during situations such as unexpected medical costs, temporary loss of family income or other emergencies.
Emergency savings should be kept in relatively liquid instruments so that the money can be accessed when required.
This can also prevent you from having to withdraw long-term investments at an unsuitable time.
Don’t Ignore Insurance
Financial independence is not only about investments.
Adequate health insurance and appropriate life insurance for earning members of the family can help protect the household from major financial shocks.
A strong financial plan should therefore combine emergency savings, insurance and long-term investments.
Keep Your Personal Investment Goal Separate
One practical strategy is to maintain a dedicated investment account or portfolio for your personal financial goal.
Instead of investing only whatever money remains after monthly expenses, treat your investment contribution as a planned part of the household budget.
For example, if ₹5,000 is available for investment each month, invest that amount first and then plan the remaining expenses around the available budget.
This can make the investment habit more consistent.
Increase Your Investment Every Year
Suppose you begin by investing ₹5,000 per month.
Instead of keeping the contribution at ₹5,000 permanently, consider increasing it whenever your financial capacity improves.
You could increase the investment after receiving additional household income, reducing unnecessary expenses or achieving other financial goals.
Even small annual increases can make a significant difference over a long investment period because the additional contributions also get time to grow.
Don’t Chase the Highest Return
A higher expected return generally comes with greater investment risk.
Therefore, selecting an investment only because it has generated high returns in the past may not be appropriate.
The investment should match the time horizon of your ₹25 lakh goal.
If the money will be required within a few years, taking substantial equity-market risk may expose the goal to unnecessary volatility.
For a goal that is 15 or 20 years away, diversified market-linked investments may have a greater role, depending on your risk tolerance.
What If You Can Invest Only ₹1,000 or ₹2,000?
Do not assume that you have to wait until you can invest a large amount.
Starting with ₹1,000 or ₹2,000 per month can help establish financial discipline. As your ability to save improves, the investment can be increased gradually.
The important thing is to begin with an amount that you can maintain consistently rather than choosing an unrealistic contribution and stopping after a few months.
Review Your Plan Every Year
Your financial situation can change over time, so review your investment plan at least once a year.
Check your current investment value, monthly contribution, expected target date, asset allocation, emergency fund and insurance coverage.
If your savings capacity increases, consider increasing the monthly investment.
If household expenses temporarily rise, it may be better to reduce the contribution for a short period rather than completely abandoning the investment plan.
Remember Inflation
₹25 lakh is a significant financial milestone, but it is important to consider inflation.
The purchasing power of ₹25 lakh today will be lower several years from now. Therefore, if your target is 15 or 20 years away, you may eventually need a larger corpus to maintain the same standard of living.
Once the ₹25 lakh target becomes achievable, consider reassessing the goal based on your future expenses, retirement requirements and inflation.
Final Takeaway
A homemaker does not need a traditional monthly salary to start building financial independence.
A disciplined saving habit, regular investing, gradual increases in contributions and sensible risk management can help create a substantial personal corpus over time.
The ₹25 lakh target should be treated as a financial goal rather than a guaranteed outcome. Starting early, remaining consistent and reviewing the strategy regularly can make the journey toward financial independence more manageable.
Disclaimer: Investment returns are not guaranteed. Market-linked investments are subject to market risks, and actual returns may differ from the illustrations used in this article. Consider your financial goals, risk tolerance, taxation and investment horizon before investing.